World Center for Strategic Studies
From closed analysis to public debate
- MONTH
- YEAR
Europe’s IPO Drain: Its Best Companies Keep Looking to America
Europe creates innovative companies but is struggling to keep them when they need serious money to grow. CER’s policy brief finds a stock-market system losing ground to the US – fragmented exchanges, weak equity investment and too few large companies capable of delivering heavyweight IPOs.
EU exchanges accounted for just 8 per cent of global IPO volumes in 2025, down from 32 per cent in 2015, while European firms increasingly look across the Atlantic for deeper capital. The danger is bigger than finance: if Europe cannot fund and list its winners at home, it risks losing corporate headquarters, strategic decision-making and control over technologies it claims are vital to its sovereignty.
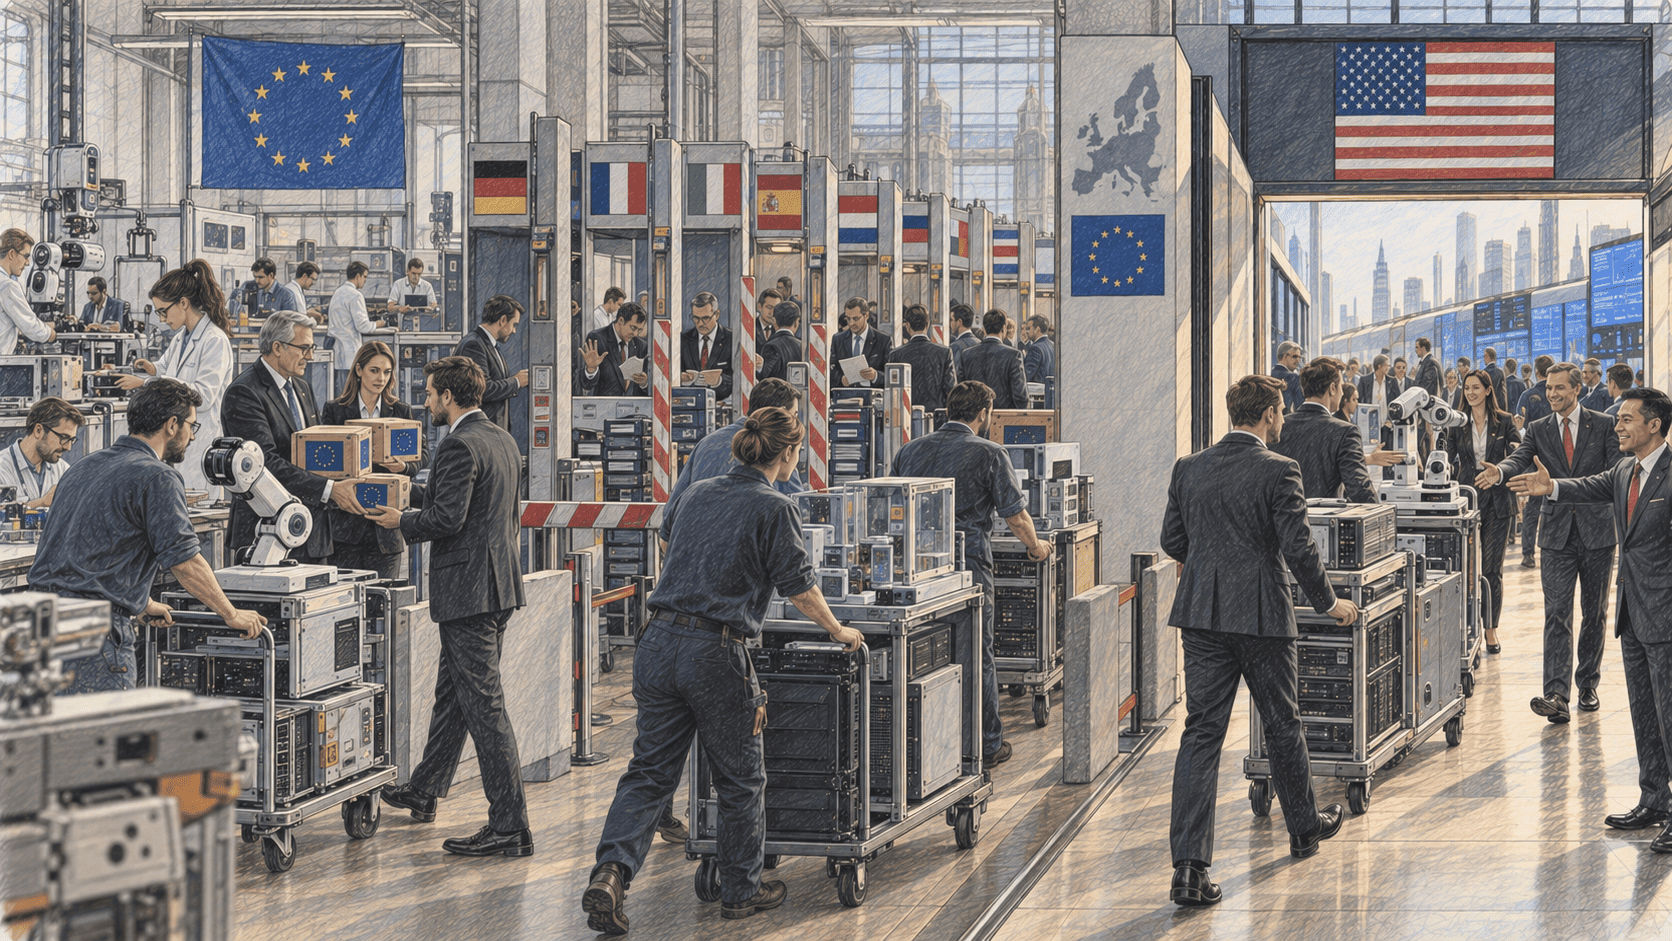
Europe saves – America invests
Europe is not short of money. Around €10 trillion of EU household wealth sits in relatively safe, low-return bank deposits.
The problem is where that money goes. European pension systems and households invest too little in equities, leaving companies with a shallower pool of capital than US competitors enjoy.
CER wants pension reform and stronger incentives for retail investment to turn more European savings into productive risk capital.
Fragmentation is choking scale
America has two dominant exchanges, a vast investor base and highly integrated market infrastructure. Europe remains carved into more than 30 exchanges alongside fragmented clearing and settlement systems.
The result is friction, divided liquidity and higher costs.
EU stock-market capitalisation stands at around 55 per cent of GDP, compared with 147 per cent in the US. Europe has money and companies – but its national markets still struggle to combine them at continental scale.
Europe’s IPOs arrive too small
The weakness is not simply that European companies leave. Too many of those that stay reach the stock market without enough scale.
More than 72 per cent of European companies listing in Europe since 2014 had a free float worth less than €100 million, compared with 49 per cent of US companies. Only 12 per cent of European listings reached €1 billion in market capitalisation at IPO, against more than 29 per cent in America.
Small listings then struggle to attract institutional investors, analyst coverage and liquidity, reinforcing the perception that European markets are second-rate destinations.
America pulls away the winners
The damage becomes particularly painful in technology and biotech.
Nearly 80 per cent of European companies that conducted IPOs in the US came from growth sectors. Companies such as Spotify and Klarna demonstrate that even successful European ecosystems can lose major listings once firms outgrow the depth of national markets.
European companies listed in America receive average valuations 3.32 times higher than those listed in Europe, although CER cautions that moving to the US does not guarantee an individual company a valuation boost.
Brussels cannot shortcut the problem
A politically engineered European Nasdaq sounds attractive, but CER warns that simply creating one exchange would not fix the underlying weakness.
Nor will loosening listing standards. Europe needs deeper investor demand, less legal and market fragmentation and stronger companies arriving at IPO stage.
A pan-European growth market could help concentrate liquidity, but only if it attracts sufficiently large, high-quality firms rather than becoming another home for tiny, thinly traded stocks.
The single market failure comes back again
Europe’s stock-market weakness starts long before an IPO.
Companies remain constrained by national regulations, tax systems, insolvency rules and product standards. Late-stage venture funding is also badly undersized – the EU has only one-tenth as many VC funds raising more than €250 million as the US.
That means promising companies can start in Europe, need foreign capital to scale and eventually discover that an American listing makes more sense. Europe pays for the innovation pipeline only to watch crucial parts of the value chain drift elsewhere.
Where this leaves Europe: Build champions or keep exporting them
CER’s prescription is demanding but straightforward – mobilise European savings, integrate capital markets and complete enough of the single market for companies to reach genuine global scale without leaving.
Europe’s sovereignty rhetoric will ring hollow if its most promising businesses still need American markets to become giants.